What Is a Class 4 Roof? Impact Resistance and Insurance Savings
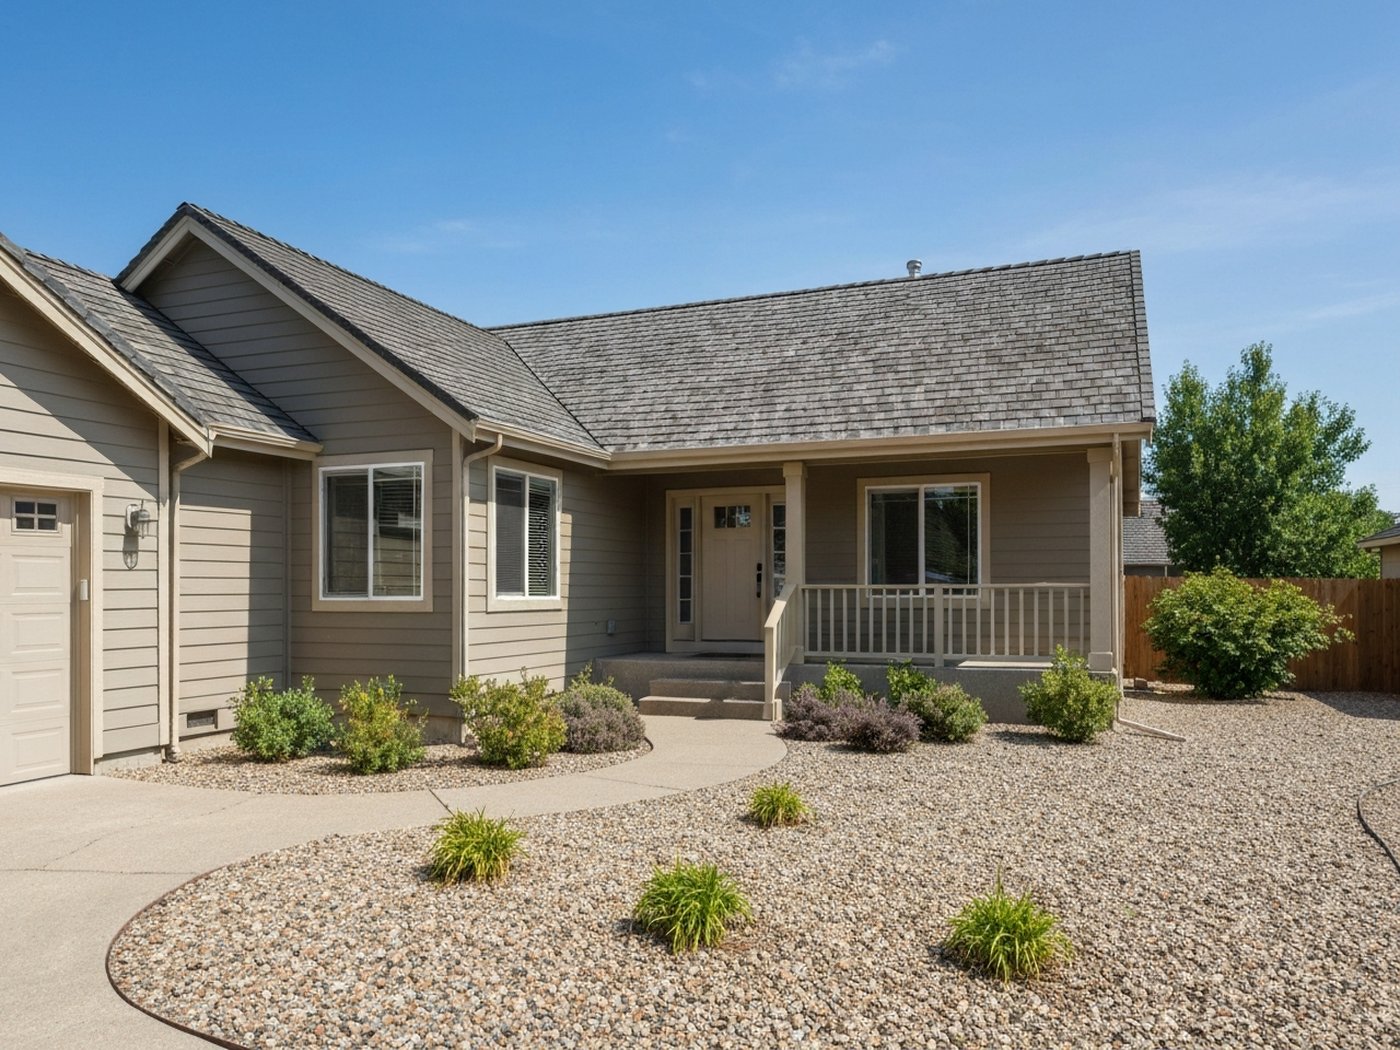
The roof question I get most often from homeowners in fire-prone areas is not strictly a fire question. Someone’s insurer mentioned a discount at renewal, or a neighbor replaced their shingles after hail and the roofer brought up Class 4. Let me work through what the rating actually is, how it connects to wildfire resilience, and what the insurance math looks like once you push past the marketing language.
What the Class 4 test actually measures
Underwriters Laboratories runs this under UL 2218, a standard developed for the roofing industry after costly hail seasons in the Midwest and Plains. The method is straightforward: steel balls of increasing diameter are dropped from 20 feet onto a flat roofing sample, and an inspector looks for visible cracks, splits, or punctures. Class 1 uses a 1.25-inch ball. Class 2, a 1.5-inch ball. Class 3, 1.75 inches. Class 4 uses a 2-inch ball. Pass all four with no visible damage, and the material earns Class 4.
The test was built for hail, and that context shapes how insurers use the rating. A hailstone hits fast, concentrated, and at a sharp angle. A Class 4 material is dense and resilient enough to take that impact without fracturing. Fractured shingles let water into the sheathing. An 8-inch hailstorm is expensive enough on its own; add interior water damage from compromised shingles and the cost compounds fast. The rating is a genuine risk-management tool, not just a marketing badge.
Class 4 vs. Class A: two different systems
This is the confusion I hear most often, and it matters a lot in fire country.
Class A is a fire resistance rating governed by ASTM E108, with UL 790 as the parallel Underwriters Laboratories standard. It measures how a roofing assembly behaves when exposed to severe external fire: resistance to ignition, rate of flame spread, and whether burning brands (simulated embers) can set the material alight. Class A is the best rating. Class B and C allow progressively more flame spread before the material self-extinguishes.
Class 4 tests only impact. Class A tests only fire resistance. A material can be Class 4 and Class A (metal standing-seam, many synthetic slate products, some SBS-modified asphalt shingles). It can be Class 4 without a high fire rating (some older or lower-quality impact-modified products). It can be Class A without earning Class 4 (standard architectural asphalt may achieve Class A as part of an assembly but fails the impact drop test). The two systems run independently of each other.
In wildfire country, the fire rating is the specification that directly addresses your exposure. Class 4 is a welcome bonus if the material earns it, but it does not substitute for a fire rating. Ask for both certifications when you are comparing quotes.
A roofer saying "it is Class 4" does not mean it is also Class A fire-rated. Ask for both certifications by name and confirm them on the manufacturer's website before you sign.
Which materials earn Class 4
Most standard asphalt shingles, including the standard three-tab and architectural grades you see on the majority of American homes, do not pass UL 2218 at Class 4. The products that do are built specifically for it.
Impact-modified asphalt shingles. Standard asphalt shingles crack under impact because the asphalt compound gets brittle as it ages. Impact-modified versions incorporate SBS (styrene-butadiene-styrene), a rubberized additive, which gives the asphalt layer elasticity. Hit it with a steel ball, and it dents rather than fractures. From the curb these look identical to standard shingles. Many earn Class A fire ratings as part of a standard roof assembly. The premium runs roughly $1.50 to $3.00 more per square foot over standard architectural shingles, though labor costs and regional pricing vary considerably.
Metal roofing. Standing-seam steel and aluminum, plus metal shingle systems, routinely earn both Class 4 impact and Class A fire ratings. A metal surface also sheds debris faster than a rough-textured asphalt field, which reduces needle and bark accumulation at the roofline. That matters when you are thinking about ember fuel. Installed cost runs from around $8 to $15 or more per square foot, depending on profile and gauge, with architectural and heavier-gauge steel at the higher end.
Synthetic slate and shake. Polymer-composite products designed to replicate wood shake or real slate can achieve Class 4 and, in many product lines, Class A fire ratings. They outlast natural wood shake by a significant margin and do not carry the fire liability that untreated cedar does. Installed pricing typically falls between $7 and $13 per square foot, though it varies by region and product complexity. Quality in this category spans a wide range. Verify that a specific product has a current UL 2218 Class 4 listing and a current UL 790 or ASTM E108 fire rating, not just marketing copy.
Concrete and clay tile. Dense and hard by nature, these often meet Class 4 without any modification and are Class A fire-rated as well. The main constraint is structural: tile adds significant weight, and older homes or additions sometimes require a framing inspection before tile is viable.
Why it matters in wildfire country
The connection between Class 4 and wildfire resilience is real but indirect, and it is worth being specific about the mechanisms.
Embers, not radiant heat or direct flame contact, are the leading cause of home loss in wildfires. IBHS (Insurance Institute for Business and Home Safety) has documented this across multiple fire events, and it shapes every piece of guidance from Firewise USA (an NFPA program) and Cal Fire. Embers drift ahead of the fire front, sometimes miles, and land on surfaces looking for fuel. A roofline with accumulated pine needles and bark chips is exactly what they find.
Metal and hard-surface synthetic Class 4 products help because their smooth, non-porous surfaces shed needles, shingle grit, and bark instead of letting it pile and pack against the shingle field. That is an indirect fire benefit: less debris means less ember fuel collecting at the seam where the roof meets the eave, which is where ignition tends to start. The direct fire benefit still comes from the Class A rating, which governs whether the roof surface itself ignites. But a fire-resistant surface that also sheds debris is meaningfully better than one that accumulates it.
This is the same logic that puts roof material near the top of wildfire home hardening guidance from IBHS, Firewise USA, and Cal Fire: address the surface (Class A), and address the fuel collection point (clean gutters and roofline).
Insurance discounts: the real picture
Most homeowners searching for Class 4 want to know whether the roof pays for itself through insurance savings. Here is the honest version.
Class 4 roofing discounts exist and in some states they are substantial. Texas is the best-known example: multiple major admitted carriers there have offered 20 to 30 percent reductions on the wind-and-hail component of the premium, because Class 4 roofs have measurably better hail-loss histories than standard shingles. Colorado homeowners have seen similar treatment after years of severe hail events along the Front Range. Carriers in the Mountain West and High Plains are generally the most active here, because hail is their primary weather exposure in those markets.
In wildfire-primary states like California, Oregon, and Washington, Class 4 alone may not trigger a specific discount. Those state frameworks tend to focus on fire hardening as a whole: vent protection, siding, zone clearance, and roof rating together rather than impact resistance in isolation. California’s “Safer from Wildfires” framework requires admitted insurers to offer mitigation discounts, but the scoring looks at the full hardening profile. Ask your insurer directly how they weight Class 4 in their rating model for your specific property.
The honest range for Class 4 discounts is roughly 5 to 30 percent of the applicable portion of your premium, and that applicable portion may be only a fraction of the total. A 25 percent discount on the wind-hail component of a premium that is itself 40 percent of your total policy is a different outcome than a 25 percent reduction across the board. Before making a financial decision that depends on an expected discount, get the actual number for your actual policy. This is educational context, not professional insurance advice. Confirm specifics with your insurer and your state Department of Insurance.
When your carrier confirms a Class 4 discount, ask what documentation they require and whether it must be submitted within a specific window after installation. Some carriers want an adjuster inspection; others accept a permit and a manufacturer's product certificate. Get the answer before the roofer's crew leaves the driveway.
Cost and the long view
A Class 4 upgrade costs more at installation. Impact-modified shingles on a 2,000-square-foot home might add $3,000 to $6,000 over standard architectural shingles at current rough regional averages. Metal or quality synthetic products could be $10,000 to $30,000 more. Get actual bids from licensed local roofers; these are reference points, not quotes.
Where the economics work over time is longevity and avoided losses. A standard asphalt shingle roof lasts roughly 15 to 25 years. A metal or quality synthetic roof typically carries 40 to 50-year manufacturer warranties (read the fine print, since those warranties often have prorated coverage and installation requirements). Fewer hail claims mean fewer deductible hits and less risk of non-renewal due to loss history. And for homeowners with serious wildfire exposure, a fire-resistant, debris-shedding roof reduces the probability of the total loss that ends the insurance relationship entirely.
A rough illustration: if your annual premium is $3,600 and your carrier offers a 20 percent reduction on the wind-hail component, which runs 35 percent of your total, the annual savings is around $252. Over 20 years, that is about $5,000, before factoring in the hail claims you avoided and the extended roof life. Run the math with your own actual premium and your carrier’s actual quoted discount. The illustration is for structure, not prediction.
Getting the credit: documentation
If you install a Class 4 roof and want the insurance discount, paperwork makes or breaks it.
Keep the manufacturer’s UL 2218 Class 4 product certificate, which is downloadable from most manufacturer sites or available through your roofer. Keep the building permit and final inspection sign-off. Take dated photos of the old roof going off and the new material going on, and photograph the product label or bundle tags before the materials are installed. Some carriers want a copy of the invoice listing the specific product by name.
When you report the new roof to your insurer, ask whether they need an in-person adjuster inspection or whether you can submit documentation electronically. Do not assume the discount applies automatically at renewal. Some carriers flag Class 4 installations in their system; others require you to request the credit each renewal cycle. If you are shopping carriers after a non-renewal, lead with the Class 4 documentation upfront. It signals a lower-risk roof before underwriting visits the property.
For a broader look at how hardening documentation and roofing upgrades interact with coverage availability, the wildfire home insurance guide covers how underwriters are shifting toward property-level risk scores rather than ZIP code alone.
The roofline reminder
A Class A, Class 4 roof is one of the best investments you can make at the top of your home. But I have done enough in-home assessments to know that a great roof over a packed gutter is still a weak point at the roofline. The gutter line, where the roof drains, is where dry needles and bark accumulate through fire season. An ember landing in that debris has everything it needs, fuel, airflow, and the fascia board right behind it.
Clean the gutters before fire season, every season. If you are surrounded by conifers and the ladder routine is not getting done reliably, a stainless micro-mesh guard that keeps needle debris out continuously is worth considering. We covered what actually stops pine needles in the best gutter guards for pine needles and fire debris guide. A better roof and a debris-free roofline are the combination, not a choice between them.
FAQ
Is Class 4 the same as Class A for fire? No. Class 4 is an impact resistance rating under UL 2218, designed to measure how a roofing material holds up against hail-sized impacts. Class A is a fire resistance rating under ASTM E108 (or UL 790), testing how a roof assembly resists flame spread and burning embers. The two systems are independent: a material can earn both, either one alone, or neither. For wildfire country, Class A directly addresses your fire exposure. Class 4 is a meaningful bonus when the material earns it alongside a Class A fire rating, but it does not substitute for one.
Will a Class 4 roof lower my homeowners insurance premium? Often yes, particularly in hail-prone states like Texas and Colorado, where many carriers have offered 20 to 30 percent reductions on the wind-and-hail portion of the premium. In wildfire-primary states, the discount framework may be organized around overall fire hardening rather than impact resistance specifically. The actual range is wide, roughly 5 to 30 percent of the applicable premium component, which may be a fraction of your total policy cost. Call your carrier, ask what documentation they require, and confirm exactly what portion of the premium the credit applies to. This is general information, not professional insurance advice; confirm specifics with your insurer and your state Department of Insurance.
Which Class 4 materials also earn a Class A fire rating? Most metal roofing, including standing-seam steel and aluminum and metal shingles. Many synthetic slate and shake products (verify the specific product’s current UL 790 listing, not just the marketing claim). SBS-modified asphalt shingles typically achieve Class A as part of a standard roof assembly. Concrete and clay tile. When getting quotes, ask your roofer for both the UL 2218 Class 4 listing and the ASTM E108 or UL 790 fire rating documentation by name, and pull them up on the manufacturer’s site yourself.
Does a full roof replacement require a permit, and does it affect insurance? In most jurisdictions, yes. The permit creates your documentation trail: licensed contractor, installation date, final code inspection. Some insurers require a valid permit before crediting a Class 4 discount. Others will accept the product certificate alone, but the permit protects you if there is ever a claim dispute about installation quality. Pull the permit, keep the inspection sign-off with your home records, and do not let a roofer talk you out of it to save a day or a fee.
Related guides
Class A Roofing Shingles: The Fire-Rated Choice for Asphalt Roofs
Class A asphalt shingles carry the highest fire rating for roofing in the US and are the baseline for any wildfire-resilient roof in a fire-prone state.
Read the guide →Class A Roof Assembly: How the Whole System Earns Its Rating
A Class A fire rating applies to the whole roof assembly, not just the shingles, and understanding the difference changes how you approach re-roofing in fire country.
Read the guide →Defensible Space Inspections: What Inspectors Look For
A straight explanation of what fire inspectors check during a defensible space inspection, zone by zone, so you can prepare before they arrive.
Read the guide →Keep ignitable debris out of your roofline
Get a free, no-obligation LeafFilter gutter-protection assessment. Fine micro-mesh keeps leaves and pine needles out of the gutters, the spot where wind-blown embers love to land. Booking through us supports this site.
Get a free LeafFilter assessment →